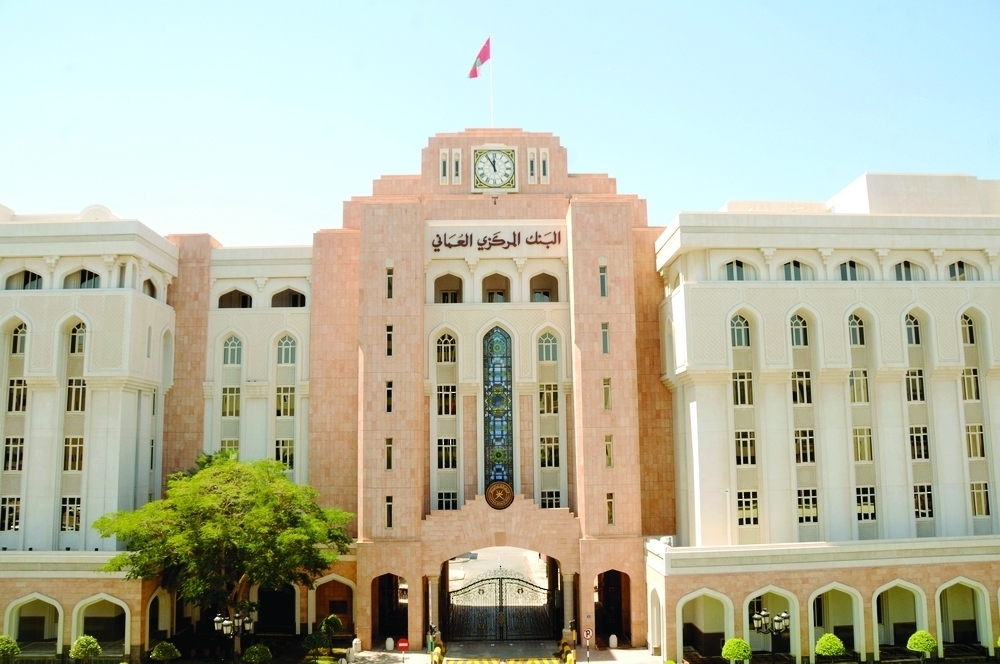


Muscat: The Central Bank of Oman (CBO) raised its repo rate by 25 basis points to 4.5 per cent effective Thursday, marking its first upward move since the repo rate was raised to 6 per cent in July 2023.
The decision followed the US Federal Reserve’s quarter-point increase on Wednesday, which lifted the target range for the federal funds rate to 3.75–4 per cent. The Fed said inflation remained elevated and that the move would support a ‘timelier return’ to its 2 per cent target.
The CBO said its decision was consistent with the fixed exchange-rate system for the Omani rial and would contribute to maintaining monetary and financial stability.
It said the increase would also help contain inflationary pressures and maintain price stability, limit undesirable cross-border capital flows and reduce exchange-rate risks for investors.
The repo rate had stood at 4.25 per cent since December 11, 2025, when the CBO made the final quarter-point reduction of the previous easing cycle.
Oman’s monetary policy closely follows US interest-rate movements because of the rial’s fixed exchange rate against the dollar and the country’s open capital account.
The CBO’s 2025 Annual Report says its policy repo rate is aligned with the upper bound of the US federal funds target range, with an additional 50 basis points to reflect differences in the risk profiles of the two economies. The latest US upper bound of 4 per cent therefore corresponds with the new 4.5 per cent CBO repo rate.
The increase comes as domestic inflation has accelerated.
Oman’s consumer price inflation reached 3.4 per cent year on year in August, according to the National Centre for Statistics and Information, while average inflation over the first eight months of 2026 stood at 2.9 per cent.
Transport recorded the largest annual price increase, at 8.5 per cent, followed by food and non-alcoholic beverages at 7 per cent and miscellaneous personal goods and services at 6.1 per cent.
For borrowers, however, the CBO’s 25-basis-point move does not necessarily translate into an identical increase in household or corporate lending rates.
Evidence from Oman’s previous tightening cycle shows that the transmission of policy-rate changes into retail borrowing costs has historically been limited.
The CBO’s 2024 Financial Stability Report noted that the repo rate reached 6 per cent in July 2023, while the overnight rial interbank lending rate rose to 5.42 per cent in December 2023 from 4.27 per cent a year earlier.
Yet the weighted average interest rate on rial lending increased only to 5.51 per cent in December 2023 from 5.38 per cent in December 2022. The CBO concluded that the pass-through to retail interest rates was ‘not complete’.
Research by the International Monetary Fund reached a similar conclusion. A 2024 IMF study found that transmission from policy rates into effective lending and deposit rates in Oman remained subdued compared with other GCC economies.
The IMF attributed the relatively weak pass-through partly to persistent banking-system liquidity, the cap on personal-loan interest rates and the structure of banks’ lending portfolios.
Those factors remain relevant as the banking system enters the latest tightening phase from a position of strong credit growth.
The latest monthly statistical bulletin currently listed by the CBO shows total outstanding credit extended by conventional and Islamic banking institutions rising 11.5 per cent year on year to RO37.4 billion at the end of May 2026, compared with RO35.3 billion at the end of 2025.
Banks also entered 2026 with sizeable liquidity buffers. At the end of 2025, the sector’s liquidity coverage ratio stood at 194.2 per cent, while its net stable funding ratio was 120.9 per cent, both above the 100 per cent regulatory threshold.
The combination of strong liquidity and historically incomplete policy transmission means the immediate effect of the new repo rate is likely to be watched first in the interbank money market and banks’ own funding costs rather than assumed to pass automatically into every loan.
The CBO’s repo facility allows banks to obtain short-term liquidity against eligible securities and is one of the central bank’s main tools for influencing short-term monetary conditions while preserving the exchange-rate peg.
The previous tightening cycle also provides a precedent for consumer protection. In its 2024 Financial Stability Report, the CBO found that a substantial increase in policy and interbank rates had produced only a modest movement in average retail lending rates.
The key indicator following Thursday’s decision will therefore be how far the higher repo rate feeds through into overnight interbank rates, deposit pricing and new or variable-rate bank lending.
With credit still growing at a double-digit pace and inflation at 3.4 per cent, the latest decision marks a clear change in the direction of monetary policy. Whether that change materially raises borrowing costs for Omani households and businesses will depend on the strength and speed of transmission through the domestic banking system.
Oman Observer is now on the WhatsApp channel. Click here